August 31, 2026 (July data)
The data released over the last month resisted easy characterization, with most of the headline improvements carrying a qualification close behind. The unemployment rate edged down to 4.1%, but the decline arrived alongside an outright loss of 23,000 payroll jobs and a labor force that continued to contract. Inflation told a similar two-sided story. Consumer prices rose just 0.1% over the month and the 12-month rate eased to 3.3%, with core prices up 0.2% and down to 2.5% over the year — all readings suggesting recent improvements on inflation. However, the latest reads of almost all price indexes suggest that inflation is still above the Federal Reserve's 2% objective. Other indicators were similarly mixed. Retail sales fell, while personal income and industrial production expanded. Against this backdrop, Federal Reserve Chairman Warsh used his first Jackson Hole address in late August to emphasize that the latest inflation readings did not yet constitute sufficient progress, leaving the path of future interest rates decidedly uncertain.
Looking under the hood with the BBKI
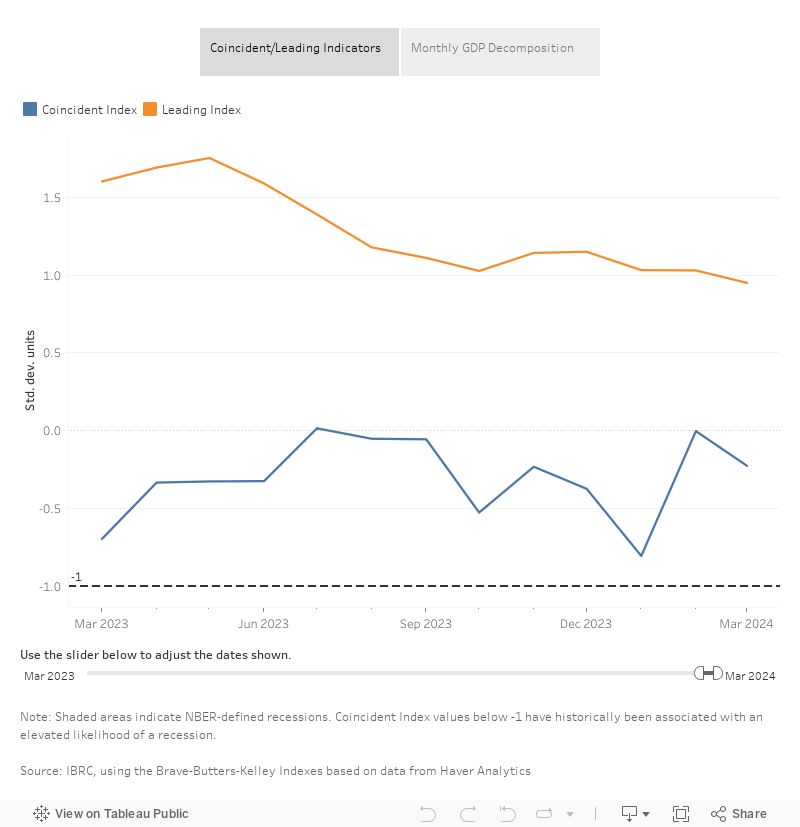
The latest release of the Brave-Butters-Kelley Indexes (BBKI) has the coincident index at 0.1 for July, up from our estimate of -0.3 for June. This reading places the economy right around trend growth, which our model estimates to be near 2.8% on an annualized basis. The improvement in the coincident index partly reflects the July readings of several component series that turned up over the month, including consumer sentiment, building permits and a decline in the unemployment rate.
Pulling this all together, the economy has returned to roughly trend-consistent momentum, but the composition of the recent data leaves the path forward unusually open. Continued developments on inflation and in the labor market are likely to be especially telling for how the economy evolves as we draw near the final quarter of the year. Whether the moderation in price growth proves durable rather than a temporary reprieve from energy markets, and whether hiring stabilizes or continues to erode, will shape both the trajectory of activity and the policy responses to it in the months ahead.
VIEW PAST RELEASES
An additional look at quarterly GDP
Get notified when the BBKI is released
Subscribe to receive a monthly email notification when the BBKI is updated.
SUBSCRIBE
What is the BBKI?
Business cycle indexes and monthly GDP growth
Because the most comprehensive measures of economic activity, such as gross domestic product (GDP), have a substantial time lag before they are published, policymakers and businessses require more timely and accurate assessments of overall economic activity in order to make better decisions. This led a group of economists from the Federal Reserve Bank of Chicago and the IU Kelley School of Business to create a set of indexes — the BBKI — that can accurately identify key turning points in economic activity earlier.
The BBKI inputs an unbalanced panel of 490 monthly measures of real economic activity plus quarterly real GDP growth extending back to January 1960. (These data broadly reflect the set of real economic activity indicators commonly used to forecast U.S. GDP growth.) The outputs include a coincident index, a leading index, and not only a measure of monthly GDP growth, but also a decomposition of it into its trend, cycle and irregular components.
The coincident index
The coincident index addresses the question: "Where are we?"
It is measured in standard deviation units and assesses the current strength of the economy. Using a threshold value of -1.0, provides a remarkably accurate (up to 99% accurate) way to gauge whether the economy is in a recession. This accuracy in gauging the strength of the economy has been shown to best many of the leading alternatives and can often come in a much timelier fashion given that the BBKI is released monthly.
The leading index
The leading index addresses the question: Where are we going?
It is a sub-component of the coincident index that isolates the economic activity that has historically been a leading signal of the trajectory of economic activity going forward. This leading index has on several occasions projected a future business cycle turning point several months before a peak or trough actually occurs — historically being the most informative about six to seven months out.
Monthly GDP growth
Each month, real GDP growth is allowed to have three separate components — each with their own separate type of dynamics — that all must add up to yield the total amount of growth or contraction.
-
Trend: This represents the very low-frequency and slow-moving component of real GDP growth. One can interpret it as the very long-run average of real GDP growth. While the trend component does not vary that much month to month, over the last several decades we have seen a noticeable decline in the long-run average of real GDP growth.
-
Cycle: This is the component of real GDP growth that reflects the business cycle. It is designed to capture systematic expansions or contractions across a variety of sectors of the economy. It is the cycle component that in many instances will be the most influential in guiding assessments about the health of the economy and public policy decisions designed to address it.
- Irregular: This component is what remains “left over,” after accounting for the trend and cycle components, to get back to the amount of growth or contraction we observed. While the BBKI methodology is designed to have the trend and cycle components reflect movements that are likely to govern the direction of growth going forward, the irregular component is designed to reflect more “one-off” or random fluctuations that are less likely to reflect where economic activity is headed in the future.
The BBKI approach identifies each of these components by breaking down the quarterly time series of real GDP and how it relates to the large set of other economic activity indicators. By leveraging the monthly indicators, it is able to construct these measures (and the aggregate) at a monthly frequency. This means the BBKI is able to provide a more detailed estimate more frequently than is reported by the U.S. Bureau of Economic Analysis.
Read more about the BBKI
Release schedule
The table below shows upcoming releases along with the data used in each release.
| Date of Release |
Monthly Data |
| October 5, 2026 |
August 2026 |
| November 2, 2026 |
September 2026 |
| November 30, 2026 |
October 2026 |
| December 28, 2026 |
November 2026 |